Shinhan Financial earns A+ for revised value-up initiative;
transparent capital allocation is key
- Shinhan Financial’s value-up 2.0 roadmap sets a benchmark for listed companies through its visibility and commitment
- Its roadmap gained legal and ethical weight as the revised value-up plan was approved by the board, aligning directors with duty of care and duty of loyalty to shareholders
- A notable drawback was the absence of the CEO at the 1Q earnings call. Chairman/CEO JIN Okdong should commit to attending future sessions, directly engaging with shareholders
Shinhan Financial Group’s value-up 2.0, announced on April 23rd, is a benchmark-setting plan that finally addresses the demand for transparent capital management. By establishing a formula-driven framework for predictable returns, the group has significantly narrowed the gap between management and shareholders. Accordingly, we are upgrading Shinhan’s previous rating on July 2024 from A0 to A+. This places Shinhan in our top tier alongside KB Financial and Meritz Financial (A+), while its peers like Woori Financial and JB Financial hold A- ratings.
The hallmark of Shinhan’s latest disclosure is its unwavering commitment to board-led governance. The roadmap was not a top-down management decree but a product of rigorous BoD oversight, with the CFO presenting to the board three times prior to its release. By institutionalizing a process where the board resolves, monitors, and communicates the plan, Shinhan has ensured accountability. KB Financial followed a similar path, refining its strategic framework through over five deep-dive sessions with its board between 2022 and 2024. This collaborative approach between management and the board is precisely what distinguishes 'A+' grade firms from those offering mere lip service.
Elevating value-up plans to the level of board resolutions transforms them from mere management presentations into binding legal commitments. This shift mandates the substantive involvement of directors, who must exercise their fiduciary duties through diligent review and recorded votes. The Commercial Code provides a clear mechanism for accountability: dissenting directors can shield themselves from liability through minute-entry (Article 399-3), whereas concurring directors are held legally accountable (Article 399-2). Such a system creates a 'procedural floor' for serious deliberation, providing the procedural legitimacy and long-term consistency that global investors demand from Korean boards.
Shinhan’s roadmap stands out for its professional depth and concrete metrics. While doubling down on its 2027 objectives—1) reaching a 10% ROE, 2) achieving a 50% shareholder return rate, and 3) reducing the total share count by 50mn. Most notably, the group announced it will now provide new rolling three-year guidance every year.
First, the ROE target was upgraded from a flat 10% to '10% or higher,' subtly signaling a move toward a 12% target by 2028. In 2025, ROE reached 9.11%, a 67bp improvement YoY, with a strategic focus on enhancing non-banking profitability. This shift reflects a strong confidence that future ROE will consistently exceed the cost of capital (approximately 10%). Most impressively, the group has linked long-term compensation for the CEO and senior management directly to key value-up metrics such as ROE (30%), ROTCE (30%), Relative TSR (20%), and NPL ratio (20%) and disclosed this structure with full transparency.
Second, Shinhan has broken new ground by removing the cap on its shareholder return rate, now aiming for a floor of 50%. Management anticipates a DPS compound annual growth rate of over 10%, backed by a transparent framework. By anchoring the payout ratio to a formulaic approach involving ROE and growth targets while prioritizing a healthy CET1 ratio, the group has institutionalized a predictable return model. This commitment to having the board regularly validate the payout levels further solidifies the procedural integrity and stability of their Value-up commitment.
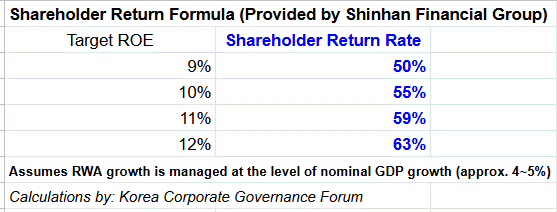
The beauty of Shinhan’s plan lies in its formulaic transparency. By pegging Risk-Weighted Asset (RWA) growth to the nominal GDP growth of 4–5%, the group has provided concrete sensitivity analysis: a 55% return at 10% ROE, scaling up to 59% at 11% ROE.
Lastly, Shinhan committed to a stable CET1 ratio floor of 13%, demonstrating its readiness to navigate evolving regulatory and market landscapes.
While the roadmap is solid, the lack of CEO presence at the Q1 results announcement remains a missed opportunity for both Shinhan and KB Financial. Global benchmarks like JP Morgan and Bank of America set a high bar, where CEOs who also serve as Board Chairs take ownership of quarterly calls. Whether it is Jamie Dimon or Brian Moynihan, these leaders view direct dialogue with analysts as a core responsibility. The same holds true for the CEOs of Goldman Sachs, Morgan Stanley, and Citigroup. To truly elevate Korean corporate governance, Chairman/CEO JIN Okdong and his peers must move beyond delegated briefings and embrace direct communication with the investment community.
May 5th, 2026
Korean Corporate Governance Forum
Chairman, Namuh Rhee

Shinhan Financial earns A+ for revised value-up initiative;
transparent capital allocation is key
Shinhan Financial Group’s value-up 2.0, announced on April 23rd, is a benchmark-setting plan that finally addresses the demand for transparent capital management. By establishing a formula-driven framework for predictable returns, the group has significantly narrowed the gap between management and shareholders. Accordingly, we are upgrading Shinhan’s previous rating on July 2024 from A0 to A+. This places Shinhan in our top tier alongside KB Financial and Meritz Financial (A+), while its peers like Woori Financial and JB Financial hold A- ratings.
The hallmark of Shinhan’s latest disclosure is its unwavering commitment to board-led governance. The roadmap was not a top-down management decree but a product of rigorous BoD oversight, with the CFO presenting to the board three times prior to its release. By institutionalizing a process where the board resolves, monitors, and communicates the plan, Shinhan has ensured accountability. KB Financial followed a similar path, refining its strategic framework through over five deep-dive sessions with its board between 2022 and 2024. This collaborative approach between management and the board is precisely what distinguishes 'A+' grade firms from those offering mere lip service.
Elevating value-up plans to the level of board resolutions transforms them from mere management presentations into binding legal commitments. This shift mandates the substantive involvement of directors, who must exercise their fiduciary duties through diligent review and recorded votes. The Commercial Code provides a clear mechanism for accountability: dissenting directors can shield themselves from liability through minute-entry (Article 399-3), whereas concurring directors are held legally accountable (Article 399-2). Such a system creates a 'procedural floor' for serious deliberation, providing the procedural legitimacy and long-term consistency that global investors demand from Korean boards.
Shinhan’s roadmap stands out for its professional depth and concrete metrics. While doubling down on its 2027 objectives—1) reaching a 10% ROE, 2) achieving a 50% shareholder return rate, and 3) reducing the total share count by 50mn. Most notably, the group announced it will now provide new rolling three-year guidance every year.
First, the ROE target was upgraded from a flat 10% to '10% or higher,' subtly signaling a move toward a 12% target by 2028. In 2025, ROE reached 9.11%, a 67bp improvement YoY, with a strategic focus on enhancing non-banking profitability. This shift reflects a strong confidence that future ROE will consistently exceed the cost of capital (approximately 10%). Most impressively, the group has linked long-term compensation for the CEO and senior management directly to key value-up metrics such as ROE (30%), ROTCE (30%), Relative TSR (20%), and NPL ratio (20%) and disclosed this structure with full transparency.
Second, Shinhan has broken new ground by removing the cap on its shareholder return rate, now aiming for a floor of 50%. Management anticipates a DPS compound annual growth rate of over 10%, backed by a transparent framework. By anchoring the payout ratio to a formulaic approach involving ROE and growth targets while prioritizing a healthy CET1 ratio, the group has institutionalized a predictable return model. This commitment to having the board regularly validate the payout levels further solidifies the procedural integrity and stability of their Value-up commitment.
The beauty of Shinhan’s plan lies in its formulaic transparency. By pegging Risk-Weighted Asset (RWA) growth to the nominal GDP growth of 4–5%, the group has provided concrete sensitivity analysis: a 55% return at 10% ROE, scaling up to 59% at 11% ROE.
Lastly, Shinhan committed to a stable CET1 ratio floor of 13%, demonstrating its readiness to navigate evolving regulatory and market landscapes.
While the roadmap is solid, the lack of CEO presence at the Q1 results announcement remains a missed opportunity for both Shinhan and KB Financial. Global benchmarks like JP Morgan and Bank of America set a high bar, where CEOs who also serve as Board Chairs take ownership of quarterly calls. Whether it is Jamie Dimon or Brian Moynihan, these leaders view direct dialogue with analysts as a core responsibility. The same holds true for the CEOs of Goldman Sachs, Morgan Stanley, and Citigroup. To truly elevate Korean corporate governance, Chairman/CEO JIN Okdong and his peers must move beyond delegated briefings and embrace direct communication with the investment community.
May 5th, 2026
Korean Corporate Governance Forum
Chairman, Namuh Rhee