We Support Decision to Suspend Solidigm Dual Listing
Formal Resolution of SK hynix Board Is Required
- BoD Chairman Koh of SK hynix should convene the board, deliberate from various perspectives on the Solidigm listing — an agenda item fatal to the share price and equity valuation — and communicate the outcome of its resolution to shareholders through disclosure
- From the standpoint of SK hynix shareholders, retaining 100% of Solidigm is preferable to selling a stake in it. Even if Solidigm requires tens of trillions of won for capex, SK hynix — with cash in abundance — need only inject that capital to Solidigm through AI Co.
On October 23rd, SK hynix disclosed the following: "Solidigm, the Company's subsidiary of US subsidiary AI.Co., has been reviewing various funding measures to expand production capacity and strengthen competitiveness; however, taking capital market conditions and other factors into comprehensive consideration, it has decided to suspend its review of a pre-IPO and an IPO."
The Forum welcomes this. In order to resolve the conflict of interest between Chairman Tony Chey and general shareholders, the Solidigm pre-IPO and IPO must of course be suspended. In this connection, the Forum asks whether this decision was the result of the board deliberating on the matter and resolving by vote — or whether it was merely the disclosure of a decision taken by the controlling shareholder Chey or by management.
There may be various options for the growth strategy and capital allocation of the company, its subsidiaries and its second-tier subsidiaries. The directors of SK hynix ought properly to debate the merits and demerits of a Solidigm pre-IPO and IPO, and from a procedural standpoint disclosure is required as to the advantages and disadvantages of the various options and the background to the final conclusion. Directors now bear the legal duty to protect the interests of all shareholders and to treat the interests of all shareholders fairly.
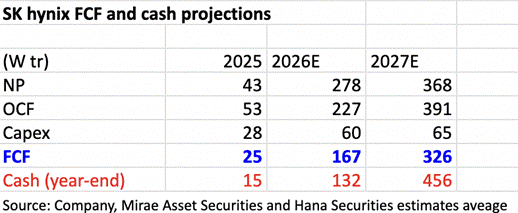
In its KCGF Opinion of October 20th, the Forum stated that from the standpoint of SK hynix shareholders, retaining 100% of Solidigm is preferable to selling a stake in it. The essence of the Solidigm dual listing is a conflict of interest between Chairman Chey and general shareholders. The only argument that could justify it is that "the money is absolutely necessary," and that premise does not hold: SK hynix is projected to generate FCF of W167tr and W326tr in 2026 and 2027 respectively. Averaging the estimates of two domestic securities firms, SK hynix will hold W132tr in cash at the end of this year and W456tr at the end of 2027. Even if Solidigm, as a second-tier subsidiary, requires tens of trillions of won for capex, the answer is for SK hynix — with cash in abundance — to contribute that capital to Solidigm through AI Co.
October 23rd, 2026
Korean Corporate Governance Forum
Chairman, Namuh Rhee

We Support Decision to Suspend Solidigm Dual Listing
Formal Resolution of SK hynix Board Is Required
On October 23rd, SK hynix disclosed the following: "Solidigm, the Company's subsidiary of US subsidiary AI.Co., has been reviewing various funding measures to expand production capacity and strengthen competitiveness; however, taking capital market conditions and other factors into comprehensive consideration, it has decided to suspend its review of a pre-IPO and an IPO."

The Forum welcomes this. In order to resolve the conflict of interest between Chairman Tony Chey and general shareholders, the Solidigm pre-IPO and IPO must of course be suspended. In this connection, the Forum asks whether this decision was the result of the board deliberating on the matter and resolving by vote — or whether it was merely the disclosure of a decision taken by the controlling shareholder Chey or by management.
There may be various options for the growth strategy and capital allocation of the company, its subsidiaries and its second-tier subsidiaries. The directors of SK hynix ought properly to debate the merits and demerits of a Solidigm pre-IPO and IPO, and from a procedural standpoint disclosure is required as to the advantages and disadvantages of the various options and the background to the final conclusion. Directors now bear the legal duty to protect the interests of all shareholders and to treat the interests of all shareholders fairly.
In its KCGF Opinion of October 20th, the Forum stated that from the standpoint of SK hynix shareholders, retaining 100% of Solidigm is preferable to selling a stake in it. The essence of the Solidigm dual listing is a conflict of interest between Chairman Chey and general shareholders. The only argument that could justify it is that "the money is absolutely necessary," and that premise does not hold: SK hynix is projected to generate FCF of W167tr and W326tr in 2026 and 2027 respectively. Averaging the estimates of two domestic securities firms, SK hynix will hold W132tr in cash at the end of this year and W456tr at the end of 2027. Even if Solidigm, as a second-tier subsidiary, requires tens of trillions of won for capex, the answer is for SK hynix — with cash in abundance — to contribute that capital to Solidigm through AI Co.
October 23rd, 2026
Korean Corporate Governance Forum
Chairman, Namuh Rhee