“Value-up proposal or a sincere apology to anguished Emart shareholders should come first”
On March 8th, Vice-chairman YJ Chung was promoted as the new Chairman of the Shinsegae Group. It’s been 18 years since he took the Vice-chairman role in 2006. Chairman Chung and his sister Yu-kyung Chung own 18.6% each of Shinsegae and Emart. Their mother, Myung-hee Lee, who exhibited excellent managerial skills owns 10% each and took on the Senior group chair role.
Shinsegae Group remarked on the recent promotions that, “the retail industry requires strong leadership and focusing on YJ Chung will allow us to navigate rapidly changing industry landscape head-on”. However, YJ Chung’s track record as Vice-chairman is very disappointing. Emart recorded annual operating loss last year and key subsidiaries also generated losses. Perhaps the Group should have focused on enhancing shareholder values or apologizing to lamenting shareholders of Emart instead of promoting YJ Chung as the Chairman of the Group. It’s a shame that with YJ Chung avoiding the nomination on the board of Emart, shareholders didn’t get a chance to evaluate and provide feedback on YJ Chung’s poor management skills.
- Value destruction: Past 5, 10 years, Emart share price has declined 59% and 70% respectively. This compares to KOSPI rising 23% and 37%, respectively.
- Excessive debt compared to market cap: Emart’s market cap has dwindled to just W2tr, while its debt has ballooned to W14tr. Excessive debt results in suppression of market capitalization.
- After effects of excessive M&As: Emart has engaged in several M&As with several trillions of Won of debt. There were irrelevant vanity deals like acquiring a US Napa winery (Shafer), and rushed deals at high prices like G-Market (that’s now generating losses). As a result, there was acquisition write-offs of W159.2bn last year. Local credit rating agencies downgraded Emart from ‘stable’ to ‘negative’ in terms of outlook as well.
- Lack of willingness to deleverage the balance sheet: Shinsegae E&C, 43% owned by Emart, is now only W83bn market cap company after a 50% decline in share price over the past year. After immense pressure from the market and creditors to de-lever, Shinsegae announced the sale of its leisure division (including 3 golf courses) for W182bn. However, the acquiror is Emart’s own subsidiary Josun Hotel and Resorts. Perhaps letting go of the prestigious Trinity Golf Club was too painful, that instead the Group shifted money from one pocket to another. Chairman Chung needs to understand how imperative it is to reduce the group leverage; it’s clear he doesn’t understand the severity of the current situation.
Emart’s PBR is 0.17x, Shinsegae E&C is 0.21x, Shinsegae is 0.38x… all of these are extremely low. Shisnegae Group and Emart should listen to President Yoon’s comments at the Korea Exchange on January 2nd 2024, asking for the reduction of the so-called Korea Discount, and participate in the Value-up program to eventually meeting global standards.
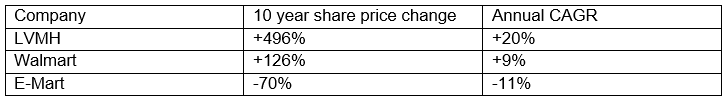
Family-owned businesses around the world, like LVMH of Europe or Walmart of US have superior long-term track record in business performance and share price. It’s possible to stay long-term focused in capex and R&D, without worrying too much about the short-term performance. Financials are also stable in family businesses as the major shareholders typically run their business conservatively. However, most family businesses in Korea exhibit the Korea Discount and have poor outcomes, and Emart specifically has excessive leverage that’s suppressing the share price for shareholders. (See below)
Key family business long term share price track record (excluding dividends)
Emart recorded its first loss since its founding; the core business is in crisis. What’s more urgent is deleveraging the balance sheet by disposing non-core assets like the winery, golf courses, baseball team, and even Starbucks Korea.
Emart’s AGM notice (as of Feb 2024) shows no plan to elect Chairman Chung as a director on its board. According to filings, top 3 paid executives in the company were not CEO or executives, but rather Chung family members. Chairman Chung was paid W1.8bn, his farther W1.5bn, and his mother at W1.5bn, while the CEO Kang was renumerated W1bn last year before his abrupt resignation. Chairman Chung’s lack of legal responsibility as an unregistered director may have contributed to the current management crisis. He has not been legally responsible for the company’s decisions, despite receiving relatively high compensation. Chairman Chung should go back to basics and fix Emart’s governance. Emart shareholders, management and board should be fully aligned and he himself should participate in the board to manage the company responsibly and honestly. If not, key man risk will continue to torment Emart shareholders.
March 11, 2024
Korean Corporate Governance Forum
Chairman
Namuh Rhee

“Value-up proposal or a sincere apology to anguished Emart shareholders should come first”
On March 8th, Vice-chairman YJ Chung was promoted as the new Chairman of the Shinsegae Group. It’s been 18 years since he took the Vice-chairman role in 2006. Chairman Chung and his sister Yu-kyung Chung own 18.6% each of Shinsegae and Emart. Their mother, Myung-hee Lee, who exhibited excellent managerial skills owns 10% each and took on the Senior group chair role.
Shinsegae Group remarked on the recent promotions that, “the retail industry requires strong leadership and focusing on YJ Chung will allow us to navigate rapidly changing industry landscape head-on”. However, YJ Chung’s track record as Vice-chairman is very disappointing. Emart recorded annual operating loss last year and key subsidiaries also generated losses. Perhaps the Group should have focused on enhancing shareholder values or apologizing to lamenting shareholders of Emart instead of promoting YJ Chung as the Chairman of the Group. It’s a shame that with YJ Chung avoiding the nomination on the board of Emart, shareholders didn’t get a chance to evaluate and provide feedback on YJ Chung’s poor management skills.
Emart’s PBR is 0.17x, Shinsegae E&C is 0.21x, Shinsegae is 0.38x… all of these are extremely low. Shisnegae Group and Emart should listen to President Yoon’s comments at the Korea Exchange on January 2nd 2024, asking for the reduction of the so-called Korea Discount, and participate in the Value-up program to eventually meeting global standards.
Family-owned businesses around the world, like LVMH of Europe or Walmart of US have superior long-term track record in business performance and share price. It’s possible to stay long-term focused in capex and R&D, without worrying too much about the short-term performance. Financials are also stable in family businesses as the major shareholders typically run their business conservatively. However, most family businesses in Korea exhibit the Korea Discount and have poor outcomes, and Emart specifically has excessive leverage that’s suppressing the share price for shareholders. (See below)
Key family business long term share price track record (excluding dividends)

Emart recorded its first loss since its founding; the core business is in crisis. What’s more urgent is deleveraging the balance sheet by disposing non-core assets like the winery, golf courses, baseball team, and even Starbucks Korea.
Emart’s AGM notice (as of Feb 2024) shows no plan to elect Chairman Chung as a director on its board. According to filings, top 3 paid executives in the company were not CEO or executives, but rather Chung family members. Chairman Chung was paid W1.8bn, his farther W1.5bn, and his mother at W1.5bn, while the CEO Kang was renumerated W1bn last year before his abrupt resignation. Chairman Chung’s lack of legal responsibility as an unregistered director may have contributed to the current management crisis. He has not been legally responsible for the company’s decisions, despite receiving relatively high compensation. Chairman Chung should go back to basics and fix Emart’s governance. Emart shareholders, management and board should be fully aligned and he himself should participate in the board to manage the company responsibly and honestly. If not, key man risk will continue to torment Emart shareholders.
March 11, 2024
Korean Corporate Governance Forum
Chairman
Namuh Rhee